Do you have to declare your imported goods?
Everything Your Company Needs to Know About the CBAM Regulation
What is it?
The CBAM (Carbon Border Adjustment Mechanism) is the European Union’s tool designed to ensure that imported products bear a carbon cost equivalent to that required of European producers.
Its legal basis is found in Regulation (EU) 2023/956, which establishes the CBAM, and in Implementing Regulation (EU) 2023/1773, which exclusively governed the transitional period (2023–2025).
Regulation (EU) 2023/956 was significantly amended by Regulation (EU) 2025/2083 (“Omnibus Package”), effective as of October 20, 2025, which streamlines the CBAM in preparation for the final regime. For this final regime, the calculation methodology and default values no longer depend on Regulation (EU) 2023/1773, but rather on a new series of regulations from 2025 — including Implementing Regulation (EU) 2025/2547 (calculation methodology) and Implementing Regulation (EU) 2025/2621 (default values).
What are your objectives?
Prevent carbon leakage.
Level the playing field between European producers and those in third countries.
Encourage global decarbonization.
Complement the European ETS by adjusting for embedded carbon in imports.
To whom does CBAM apply?
- Any company that imports products listed in Annex I of Regulation 2023/956.
- Goods brought into the EU customs territory, continental shelves, and offshore structures.
- Importers established in the EU and those not established in the EU (through an indirect representative).
- Military activities.
- Countries fully integrated into the ETS: Iceland, Liechtenstein, Norway, and Switzerland.
- Excluded territories: Ceuta, Melilla, Livigno, Büsingen, Helgoland.
Electricity imported from fully integrated grids.
Transitional Period (2023–2025)
- Does not apply to shipments whose total value per DUA does not exceed €150. (Art. 2.3).
(“One shipment = one DUA”).
Permanent Period (starting in 2026)
Imports of CBAM products totaling less than 50 metric tons per year are exempt.
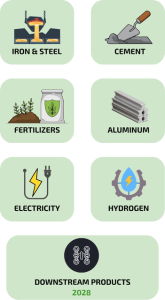
What kind of products are subject to CBAM?
- Subheading 26011200
Includes iron ores and their concentrates, except for roasted pyrite and sintered ores. - Chapter 72 — Iron and Steel Castings
This chapter covers numerous steel products subject to CBAM. Among them:
- 7201 – Pig iron in ingots, blocks, or other primary forms.
- 7202 – Ferroalloys (except those specifically excluded).
- 7203 – Iron obtained by direct reduction; sponge iron and similar products; iron with a purity of ≥ 99.94%.
- 7204 – Waste, scrap, and ingots obtained from their remelting.
- 7205 – Iron or steel shot and powder.
- 7206 – Intermediate products of iron or steel.
- 7207 – Semi-finished products of iron or steel in various forms.
- 7208 – Hot-rolled, uncoated products of non-alloy steel, with a width of ≥ 600 mm.
- 7209 – Cold-rolled, uncoated products of non-alloy steel, with a width of ≥ 600 mm.
- 7210 – Coated (galvanized, etc.) rolled products of non-alloy steel, with a width of ≥ 600 mm.
- 7211 – Rolled products of non-alloy steel with a width of less than 600 mm, uncoated or coated.
- 7212 – Coated rolled products of non-alloy steel, with a width of less than 600 mm.
- 7213 – Wire of iron or non-alloy steel.
- 7214 – Bars of iron or non-alloy steel, rolled, extruded, or forged.
- 7215 – Other bars and profiles of iron or non-alloy steel.
- 7216 – Shapes of iron or non-alloy steel not included in other headings.
- 7217 – Wire of iron or non-alloy steel.
- 7218 – Stainless steel in primary or intermediate forms
- 7219 – Stainless steel flat-rolled products with a width of ≥ 600 mm.
- 7220 – Stainless steel flat-rolled products with a width of < 600 mm.
- 7221 – Stainless steel wire.
- 7222 – Stainless steel bars and profiles.
- 7223 – Stainless steel wire.
- 7224 – Alloy steels in ingots or primary forms (including intermediate forms).
- 7225 – Alloy steel rolled products with a width of ≥ 600 mm.
- 7226 – Alloy steel rolled products with a width of less than 600 mm.
- 7227 – Alloy steel wire.
- 7228 – Bars, shapes, and perforated tubes of alloy or unalloyed steel.
- 7229 – Alloy steel wire.
Supplementary Headings of Chapter 73
- CN 7301 – Rails, metal ties, welded sections, and similar products for railway infrastructure.
- CN 7302 – Railway track components: switches, guard rails, plates, ties, and other structural elements.
- CN 7303.00 – Tubes and hollow sections of cast iron or steel.
- CN 7304 – Seamless tubes of iron or steel.
- CN 7305 – Longitudinally welded large-diameter tubes (> 406.4 mm).
- CN 7306 – Spiral-welded or straight-welded tubes, in various configurations.
- CN 7307 – Pipe fittings: couplings, elbows, sleeves, and connectors.
- CN 7308 – Steel structures and parts of structures (bridges, frames, panels, railings, etc.).
- CN 730900 – Tanks and containers of iron or steel ≤ 300 l, without special lining or insulation.
- CN 7310 – Barrels, drums, cans, and similar containers ≤ 300 l.
- CN 731100 – Containers for compressed or liquefied gases.
- CN 7318 – Steel fasteners and fastening elements: screws, nuts, washers, pins, etc.
- CN 7326 – Other iron or steel articles: mechanical parts, discs, brackets, springs, etc.
Exclusions from the CBAM Scope (Iron and Steel)
- 72022000 – Ferrosilicon
- 72023000 – Ferrosilicomanganese
- 72023010 – Ferrosilicomanganese (specific heading)
- 72023090 – Other ferrosilicomanganese
- 72024100 – Ferrosilicon-chromium
- 72024900 – Other ferrochromium
- 72025000 – Ferrosilicon-chromium
- 72026000 – Ferrosilicon-molybdenum
- 72027000 – Ferrosilicon-tungsten
- 72028000 – Ferrosilicon-titanium
- 72029100 – Ferrosilicon-magnesium
- 72029200 – Ferrosilicon-calcium
- 72029300 – Ferronickel
- 72029900 – Other ferroalloys, not elsewhere classified
- 7204200 – Iron or steel scrap and ingots made from it.
- CN 25070080 – Kaolinitic clays other than kaolin. Uncalcined clays under this code are considered to have implicit zero emissions; however, they must be reported in the MAFC report without the need for additional information from the manufacturer.
- CN 25231000 – Unground cement and clinker.
- CN 25232100 – White Portland cement, including artificially colored varieties.
- CN 25232900 – Other Portland cements.
- CN 25233000 – Aluminous cements.
- CN 25239000 – Other hydraulic cements.
- CN 7601 – Unwrought aluminum.
- CN 7603 – Powders and flakes.
- CN 7604 – Bars and profiles.
- CN 7605 – Wire.
- CN 7606 – Sheets and strips with a thickness > 0.2 mm.
- CN 7607 – Thin sheets with a thickness of ≤ 0.2 mm (excluding the backing).
- CN 7608 – Aluminum tubes.
- CN 76090000 – Aluminum pipe fittings (connectors, couplings, etc.).
- CN 7610 – Aluminum structures and parts of structures for construction.
- CN 76110000 – Tanks for compressed or liquefied gas ≤ 300 l.
- CN 7612 – Metal containers and receptacles ≤ 300 l, with or without lining.
- CN 76130000 – Containers for liquefied or compressed gas.
- CN 7614 – Aluminum electrical conductors and cables.
- CN 7616 – Other manufactured articles: fasteners, screws, clamps, rings, etc.
- CN 28080000 – Nitric acid and sulfonitric acid.
- CN 2814 – Anhydrous ammonia or ammonia in aqueous solution.
- CN 28342100 – Potassium nitrates.
- CN 3102 – Mineral or chemical nitrogen fertilizers.
- CN 3105 – Fertilizers containing two or three primary nutrients (N, P, K), as well as fertilizers in tablet form or in packages weighing ≤ 10 kg.
Exclusion:
- 31056000 – Fertilizers containing only phosphorus and potassium
CN 27160000
CN 28041000
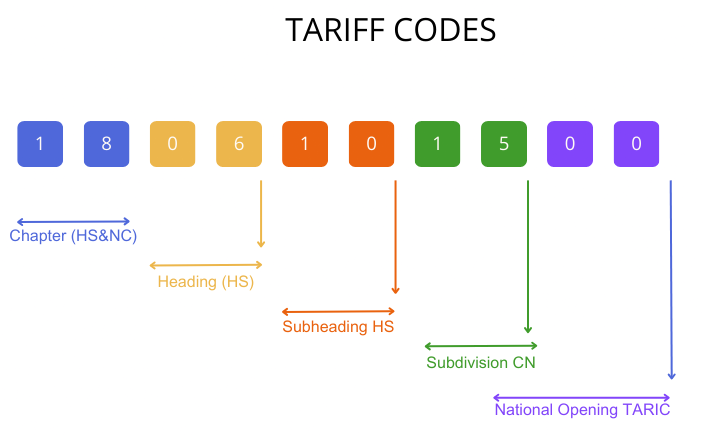
What is the CN Code?
The CBAM is linked to the CN Code (Nomenclature Code) to identify the products that are subject to this mechanism.
The Combined Nomenclature (CN) is the eight-digit code system of the European Union, which includes the Harmonised System (HS) Code together with other EU-specific subdivisions. The CN Code is used to refer to the tariff code of a product, playing a crucial role in the identification and classification of products in international trade.
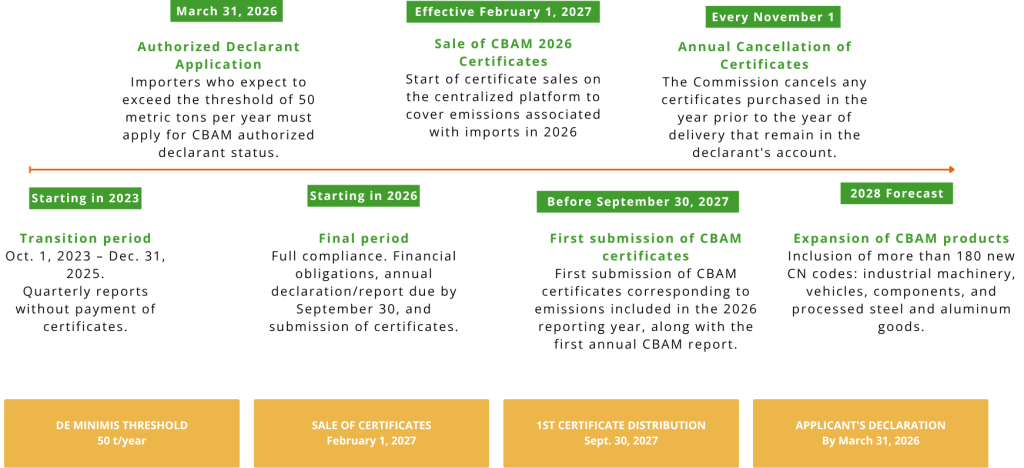
What are the implementation periods for this regulation?
TRANSITIONAL PERIOD
01/10/2023 - 31/12/2025-
CBAM Transitional Registry
-
Quarterly emissions report (no payment required)
FINAL PERIOD
01/01/2026 to 2034-
Application for Authorized Declarant Status
-
CBAM Registration
-
Purchase of CBAM certificates
-
Annual CBAM declaration
-
Submission of CBAM Certificates
-
Verification by an External Agency
Who can be a declarant?
According to Regulation (EU) 2023/956 and the 2025 amendments:
- Importer established in the EU
– Must apply for authorization before importing CBAM goods. - Indirect customs representative
– Required when the importer is not established in the EU.
– May assume this role if authorized by the established importer. - Indirect representative for “de minimis” importers (< 50 metric tons)
– Even if the importer is exempt, the representative must be authorized if they file customs declarations.
The following individuals may not act as declarants:
- Direct customs representatives.
Sanctions
TRANSITIONAL PERIOD
Oct 2023 – Dec 2025-
Do not report your emissions.
-
Failure to submit the report by the deadline.
-
Submission of an incorrect or incomplete report without subsequent correction.
FINAL PERIOD
Starting in January 2026-
Failure to submit the required number of CBAM certificates.
-
Importing without being an authorized declarant and exceeding 50 metric tons per year (penalty on all emissions).
-
Incorrect or incomplete annual declaration that has not been corrected.
-
Importing goods without complying with CBAM obligations.
In accordance with Article 26 of Regulation (EU) 2023/956 and Article 16 of Regulation (EU) 2023/1773, penalties will be imposed as of the Regulation’s entry into force in October 2023 on those who:
- For authorized declarants
If they fail to submit CBAM certificates by September 30, they will pay a penalty equivalent to the ETS excess emissions penalty: €100/t CO₂e, indexed annually to the European consumer price index since 2012 (Article 26 of Regulation (EU) 2023/956, in conjunction with Article 16 of Directive 2003/87/EC). Payment of the penalty does not exempt the party from the obligation to submit the outstanding allowances.
Example: An authorized reporter with 500 metric tons of CO₂e emissions who fails to surrender their allowances by September 30, 2027, faces a penalty of approximately 50,000 € (at the base rate of 100 €/metric ton), without being released from the obligation to surrender the outstanding allowances. - For NON-authorized importers
If they exceed 50 metric tons without authorization, they pay a penalty calculated on the total imported emissions—not just the excess—at a rate that can be up to five times the standard rate. After paying, they are released from the obligation to report for that year.
Example: An unauthorized importer with 300 metric tons of CO₂e emissions could face a penalty ranging from €30,000 to €150,000, depending on the rate applied by the competent authority.
What are the data for the Calculation of Real Values?
Required data: CN codes, identification of the production process, electricity consumption by stage, raw material consumption, and other relevant factors. Suppliers must report the methodology used to calculate emission factors.
When actual values are not available, default values are applied with a 10% surcharge in 2026, 20% in 2027, and 30% starting in 2028 (a fixed annual increase of 1% for fertilizers).
CBAM Services We Offer at Tandem HSE
Full Service
Comprehensive service from start to finish, from preliminary consulting to the registration and follow-up of the declaration.
Aimed at companies that want to outsource 100% of tasks
Continuous support
Support service and managed through a pool of hours according to the order of consultations.
Aimed at companies that want to make the declarations themselves, but need punctual and continuous support.
CBAM Training
Face-to-face and virtual in-company training and elearning to train workers.
Aimed at companies with large-workforce and capacity that want to train their workers.
CBAMate software
SaaS platform to self-manage returns.
Aimed at companies that want to manage returns in a more intuitive way and manage the file .xml
Why Tandem HSE?

Clear communication and expert support
Our service is designed to be clear and accessible, ensuring smooth communication and close support at all times.

Adapting to regulatory changes
We stay up-to-date with CBAM's regulatory changes, ensuring your business meets the latest requirements effortlessly.

Using your own tool – CBAMate
We have our own SaaS platform, CBAMate, which simplifies CBAM management, optimizes processes, improves efficiency, and reduces the risk of declaration errors.

End-to-end monitoring
We accompany you throughout the process, from data collection with suppliers to reporting, ensuring compliance and efficiency.

Market Consulting
We analyze the impact of CBAM on your supply chain and purchasing strategies, helping you make informed decisions and optimize costs.

CBAM Certified Price Simulator
Our tool allows you to accurately calculate the cost of CBAM certificates, facilitating financial planning and strategic decision-making.
Frequently asked questions
In the case of installations or operators located in third countries, the CBAM regulations also apply, and they must comply with the corresponding obligations.
Competent authorities vary according to the context, but in the framework of the CBAM, it refers to the authorities in charge of the administration and supervision of the system, which may vary from one country to another within the European Union.
Yes, amendments and corrections to CBAM reports are allowed within a specific timeframe after each quarter. However, it is important to comply with the requirements and deadlines set for these modifications.
Incomplete or incorrect reporting may result in negative consequences, such as sanctions or reviews by competent authorities. It is important to ensure the accuracy and completeness of CBAM reports.
The Transitional CBAM Registry is interoperable with electronic systems and processes related to carbon emissions reporting and monitoring, which facilitates the integration of information and data in the framework of the EU’s Carbon-Border Adjustment Mechanism (CBAM). This enables the sharing of relevant information and ensures compliance with CBAM regulations.
In the event of a temporary failure of the Registry’s electronic portal systems, it is important that the competent authorities take steps to restore the functionality of the system as soon as possible. During a failure, reporting and other CBAM-related operations may be affected. However, the regulations usually set deadlines for reporting, so it is important to comply with these deadlines even in case of temporary failures, and to notify the relevant authorities of any technical difficulties.
From the European Commission
For each quarter from 1 October 2023 to 31 December 2025, the reporting reporter shall submit CBAM reports to the CBAM Transitional CBAM register (CBAM TR) no later than one month after the end of that quarter.
During the transitional period, importers of CBAM goods do not need to obtain special authorisation to import these products into the EU. Customs authorities will inform importers of their reporting obligations at the time of import.
They do need to register in the CBAM Transitional Register in order to be able to submit the quarterly CBAM report.
No, verification by an external independent body will only be mandatory from 2026.
Non-EU producers must provide data on emissions embodied in CBAM products to EU importers. If this information is not available at the time of import, importers can use default values to calculate emissions. In addition, non-EU production facilities can register to facilitate emissions reporting, simplifying compliance for importers of CBAM products from these facilities.
A carbon price is the amount of money paid in a third country as part of a carbon emissions reduction programme. It can take various forms, such as taxes, fees or emission allowances in a greenhouse gas emissions trading system.
Customs authorities shall not permit the importation of goods by any person who is not an authorised declarant for the purposes of CBAM.
The CN codes of my imported products can be found in the SADs cleared during the quarter under obligation. In addition, it is also possible to find them in the product sheets, consult customs or contact the manufacturer directly.
The De Minimis exemption applies considering both the total value per shipment and the total value of different CN codes in one shipment. In other words, if in one shipment you import two products with different CN codes for a total value (between the two products) of €150, you must report it. Only if the total value of those products is below €150, then you do not need to report it.
Examples:
- Case 1: In your shipment, you have X products not subject to CBAM, each with a nominal value of Y euros. They are not relevant for the application of the De Minimis exemption. You also have a transport container of Portland cement identified by its CN code (2523 21 00), and its total value does not exceed EUR 150. The De Minimis exemption still applies, i.e. you do not have to declare it.
- Case 2: In your shipment, you have X goods not subject to CBAM, each with a nominal value of Y euros. They are not relevant for the application of the De Minimis exemption. You also carry one tonne of white Portland cement (CN code 2523 21 00) and one tonne of other Portland cement (CN code 2523 29 00). The value of each CBAM-covered product is EUR 120. The total value of the products subject to CBAM in your shipment exceeds €150.
No, quarterly CBAM reports must be submitted when imports of any of the CBAM products (products listed in Annex I of Regulation (EU) 2023/956) have taken place during the relevant quarter.
As from 1 February, in the CBAM Transitional Registry, declarants can use the ‘Request Delayed Submission’ function to obtain an additional 30 days. They should select ‘Requested by Declarant (technical error)’. Late submissions due to technical problems are considered justified, with no negative consequences. Submission is encouraged as soon as the technical problems are resolved.
- Use the direct link to the CBAM Transitional Registry: https://cbam.ec.europa.eu/declarant/
- Before accessing, please clear your browser cache, restart your browser or use incognito mode.
- If problems persist, this may be due to system upgrades, which can cause temporary outages. It is recommended that you try again after a reasonable time.
WHAT OUR CUSTOMERS SAY
‘Fast and efficient service’.
"Professional, fast and tailor-made.
"We are happy with the treatment and follow-up we have received.
"Explanation of the procedure easy and understandable. Fast and efficient service.
‘Very good service’.
‘Very friendly and attentive staff and perfect service’.
"Núria has a very good command of both the CBAM platform and all the concepts necessary to carry out the quarterly declaration successfully.
The excel tool they offer to collect data from manufacturers is also very useful and easy to understand.
The team in general is always ready to solve any doubt that may arise".